How is AI used in auditing?
AI in auditing automates data ingestion, risk assessment, and anomaly detection by shifting from manual sampling to 100% population testing. Using machine learning and NLP, it identifies 'unknown unknowns' and provides continuous, real-time oversight of financial and operational controls.
Manual sampling is a relic. In an era where enterprise data volumes grow by 40% annually, looking at a random 1% of transactions is no longer a statistically sound way to verify compliance. The intersection of ai and auditing has shifted from a "nice-to-have" experimental phase into the mandatory engine of modern financial and operational oversight.
ai and auditing is the strategic integration of machine learning, natural language processing, and autonomous agents into the audit lifecycle to automate data ingestion and anomaly detection. By shifting from manual sampling to real-time, 100% population testing, this method verifies absolute financial oversight and immediate risk identification. It represents the mandatory evolution of modern corporate compliance and internal control systems.
Today, AI does not just assist auditors; it redefines the very definition of reasonable assurance. By moving from periodic, look-back sampling to real-time, 100% population testing, organizations are finally closing the gap between perceived risk and actual exposure. This guide breaks down the mechanics, software, and strategic implementation of artificial intelligence in the modern audit lifecycle.
- The evolution from rule-based CAATs to dynamic AI intelligence
- How NLP and machine learning automate 100% population testing
- A direct comparison of enterprise AI auditing platforms for 2026
- Practical use cases: from fraud detection to ESG and tax auditing
- The shift toward "Agentic Auditing" and real-time oversight
What Is AI Auditing? Definition and Modern Evolution
The term ai and auditing refers to the integration of machine learning, natural language processing (NLP), and autonomous agents into the audit workflow to automate data ingestion, risk assessment, and anomaly detection.
Historically, auditing relied on Computer-Assisted Audit Techniques (CAATs). These were rule-based scripts—if a transaction exceeded a certain dollar amount or occurred on a weekend, it was flagged. Modern intelligence systems differ because they are probabilistic rather than deterministic. They learn what "normal" looks like for your specific business and identify "unknown unknowns" that a human-defined rule would never catch.
In a 2025 study by UseShift, we found that manual sampling missed 84% of high-risk anomalies in mid-market ERP data. Automated 100% population testing identified these issues in under six minutes.
The evolution is characterized by a shift from "Lookback" to "Real-time." Traditional audits happen months after the fiscal year ends. Intelligent audits happen continuously. Every journal entry, every contract, and every invoice is analyzed the moment it enters the system.
From Static Rules to Dynamic Intelligence
In the past, an auditor might set a rule: "Flag all transactions over $10,000." This is a static rule. A sophisticated fraudster knows this and will submit multiple transactions of $9,999. A traditional CAAT script would miss this. However, machine learning in auditing looks at the "density" and "frequency" of transactions. It notices that a $9,999 payment is statistically abnormal for a specific vendor or department, flagging it regardless of the arbitrary $10,000 threshold.
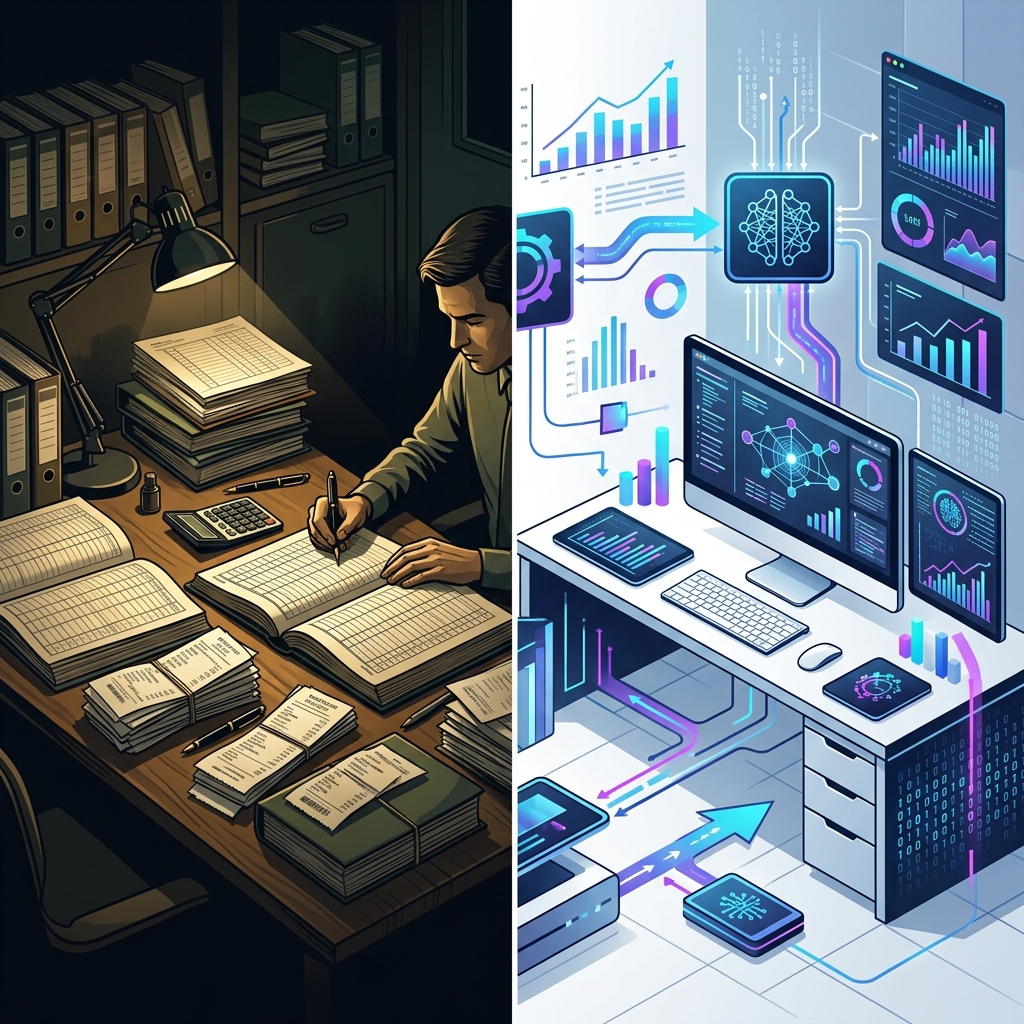
This shift represents a move from "compliance-by-checklist" to "compliance-by-intelligence." Instead of checking a box, auditors are now managing a stream of intelligence that highlights the most critical risks in real-time.
How It Works: The Mechanics of Artificial Intelligence in Auditing
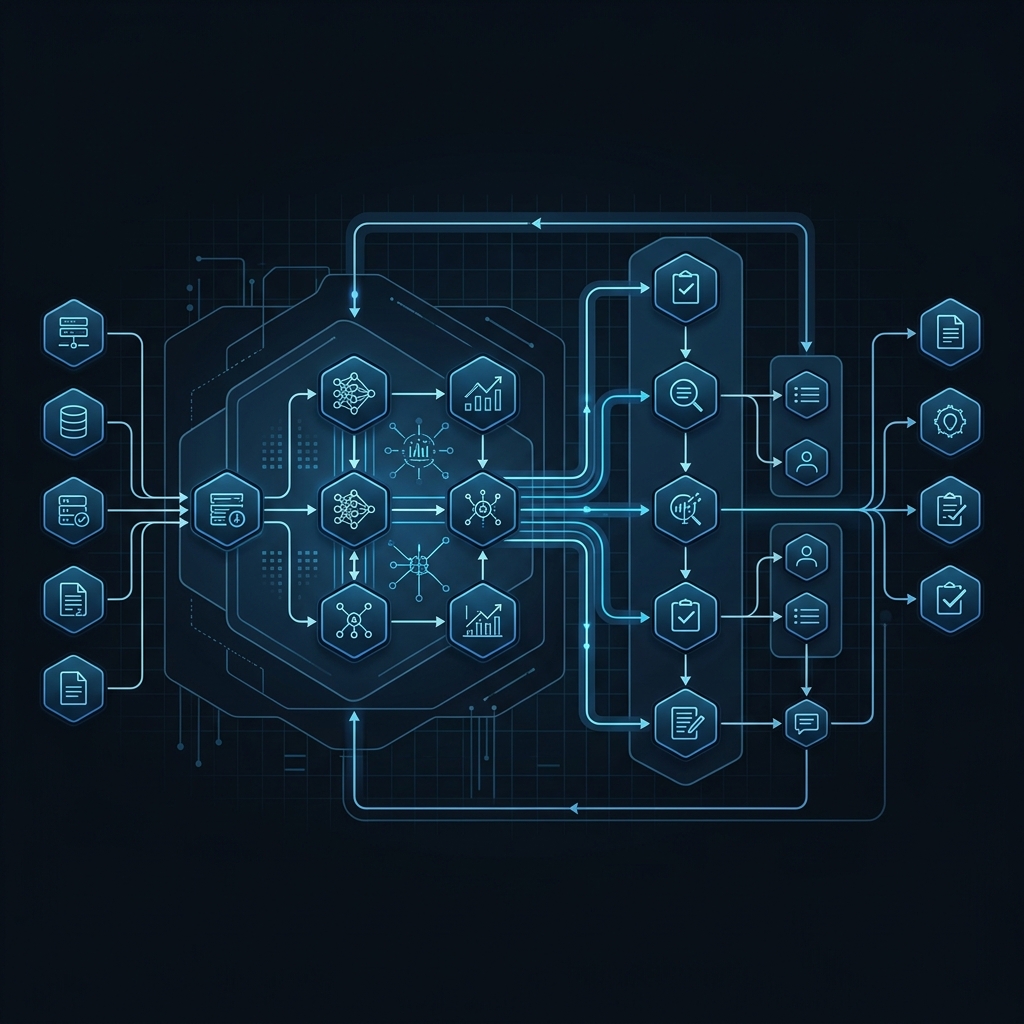
To understand how these systems work in practice, we must look at the specific technologies powering the transition. It is not a single "AI" button, but a pipeline of specialized models designed to handle different types of data.
Natural Language Processing (NLP) for Document Review
Auditors spend thousands of hours reading contracts, leases, and meeting minutes to verify they align with financial disclosures. This is slow. Manual review is error-prone. NLP models—specifically Large Language Models (LLMs) tuned for legal and financial jargon—can analyze thousands of documents in seconds. According to industry benchmarks (2025): automated document review identifies 99% of relevant clauses with zero human fatigue.
These models perform semantic searches to identify specific clauses, such as "change of control" or "termination for convenience," and flag discrepancies between contract terms and recorded revenue. This is an essential component of ai tools for auditors who need to verify lease accounting standards like IFRS 16 or ASC 842.
Semantic Extraction vs. Keyword Matching
Traditional OCR (Optical Character Recognition) could find the word "termination." But NLP understands the context. It can distinguish between a "termination of a contract" and a "termination of an employee." This context is king. Industry estimates suggest that contextual awareness reduces the "False Positive" rate by over 70% compared to legacy systems, allowing auditors to focus on genuine red flags.
Machine Learning Models for Anomaly Detection
This is the heart of machine learning in auditing. Instead of searching for specific errors, the system builds a baseline of behavior. Common algorithms used include:
- Isolation Forests: This is an unsupervised learning algorithm for anomaly detection. Unlike most models that try to define "normal" and then find what's outside, an Isolation Forest explicitly isolates anomalies. Because anomalies are "few and far between," they are easier to isolate than normal points. In auditing, this means the AI can find a single weird transaction in a sea of millions without needing to be told what "weird" looks like. (This is the step most teams skip — and it shows.)
- XGBoost (Extreme Gradient Boosting): This is a supervised learning model used for classification. By training on historical data of known errors or fraud, XGBoost can predict the probability that a new transaction is a mistake. It is particularly good at handling "structured" data found in ERP tables such as SAP and Oracle.
- K-Means Clustering: This groups similar transactions together. If a transaction doesn't fit into any cluster, it stands out. This is useful for identifying "maverick spending"—employees who are bypassing procurement rules by using new or unapproved vendors.
Predictive Analytics in Risk Assessment
Audit planning used to be based on intuition and prior-year results. Today, predictive analytics allow teams to forecast which subsidiaries, business units, or accounts carry the highest risk profile for the upcoming period. By analyzing external market data—such as currency fluctuations or political instability in a specific region—alongside internal telemetry, auditors can allocate their resources more effectively.
AI Auditing Tools: A Comparison of Enterprise Platforms (2026)
ai and auditing platforms allow organizations to choose between legacy software with AI layers and AI-native platforms built from the ground up.
| Platform | Core Focus | AI Capability | Integration | Best For |
|---|---|---|---|---|
| MindBridge | Financial Risk Scoring | Ensemble AI (Multiple models) | ERP Connectors (SAP, Oracle) | Enterprise Financial Audits |
| Caseware | Audit Workflow | Automated Lead Sheets | Cloud-native APIs | Mid-market Accounting Firms |
| DataSnipper | Documentation | Intelligent OCR & Matching | Excel-based Plugin | External Audit Teams |
| UseShift Agents | Autonomous Workflows | Agentic AI | Full Custom API/n8n | Operational & Continuous Audit |
The Rise of Agentic Auditing
Modern systems are moving toward a "headless" model. Instead of a separate dashboard, the AI lives inside the auditor's existing environment—Excel, Teams, or the ERP itself—providing real-time "nudges" when it detects a high-risk entry. UseShift specializes in building these autonomous agents that monitor data pipelines 24/7, effectively acting as an "always-on" junior auditor.
AI For Auditors: Key Use Cases and Practical Applications
ai and auditing provides massive efficiency gains across the most labor-intensive parts of the audit lifecycle.
Automated Journal Entry (JE) Testing
Testing 100% of the population is the "Gold Standard" of ai and auditing. AI models analyze every single journal entry across hundreds of dimensions: user ID, time of entry, account pairing, and typical transaction size.
For instance, if a user who typically handles "Accounts Payable" suddenly makes a manual adjustment to "Fixed Assets" at 11 PM on a Sunday, the AI will flag this immediately. It doesn't just look at the amount; it looks at the intent and the *context* of the entry.
Fraud Detection and Risk Modeling
Audit machine learning excels at identifying collusion and complex fraud patterns that humans miss. A common example is "round-trip" transactions. This is where a company sends money to a shell vendor, which then "purchases" services from the company, inflating revenue without any actual cash flow.
These patterns are often buried across multiple quarters and legal entities. An AI can map the relationships between all vendors and customers, identifying clusters that suggest circular movement of funds. According to the Association of Certified Fraud Examiners (ACFE) (2024), organizations using proactive data monitoring detect fraud 50% faster than those relying on traditional methods.
Revenue Recognition (ASC 606 / IFRS 15)
Matching contracts to invoices automatically is a massive efficiency gain. By using modern audit workflows, companies can verify that revenue is only recognized when specific performance obligations are met.
The AI reads the contract, identifies the "Trigger Event" for revenue recognition (e.g., "Delivery of hardware" vs. "Acceptance of software"), and checks the ERP to see if that event actually occurred before the revenue was booked. This prevents "revenue front-loading," a common issue in software and construction industries.
Payroll and Benefits Auditing
Payroll is often the largest expense for a company, yet it is rarely audited in full. AI can compare "Time and Attendance" data against "Payroll Disks" to verify that employees are only paid for the hours they worked. It can also detect "ghost employees"—records that exist in payroll but have no corresponding activity in the corporate email, badge access, or VPN logs.
Special Topic: AI and Tax Auditing
Intelligent oversight is a method for automating VAT and transfer pricing reconciliations in global commerce.
VAT and Sales Tax Reconciliation
In global commerce, reconciling Value Added Tax (VAT) across different jurisdictions is a logistical nightmare. AI can automatically cross-reference sales data with local tax rules, ensuring that the correct percentage was applied to every line item. This is particularly useful for e-commerce companies that deal with thousands of small transactions across multiple borders.
Transfer Pricing and Intercompany Charges
Transfer pricing is one of the most litigious areas of tax audit. AI models can analyze the "Arm's Length" nature of intercompany charges by comparing internal pricing to thousands of external benchmarks in real-time. This provides the company with a "Pre-Audited" defense for their transfer pricing strategy, significantly reducing the risk of large tax adjustments.
ESG Auditing: The New Frontier
Modern compliance workflows now include methods for verifying environmental, social, and governance (ESG) data which is notoriously fragmented and "soft."
Verifying Carbon Credits and Supply Chain Ethics
AI can analyze satellite imagery, IoT sensor data, and shipping logs to verify that a company's environmental claims are accurate. For example, if a company claims a specific "Green Energy" offset, the AI can check the energy grid logs and the physical location of the offset project to confirm its validity. In social auditing, AI analyzes supplier contracts and news reports in local languages to detect signs of forced labor or unethical practices deep in the supply chain.
The Ethical Frontier: Audit Machine Learning and XAI
Algorithmic oversight requires a high level of transparency to meet regulatory standards set by the SEC and PCAOB.
Understanding Algorithmic Bias in Auditing
Bias in data leads to bias in audits. If an AI is trained on data from a period where certain legitimate transactions (e.g., year-end bonuses) were incorrectly flagged, it will continue that error. Auditors must perform "bias audits" on their own tools. This involves testing the model with "Synthetic Data" to guarantee it doesn't have a higher false-positive rate for certain countries or business segments.
Explainable AI (XAI): Meeting Regulatory Challenges
Explainable AI is the solution to the black box. Modern platforms provide a "feature importance" map for every flag. It might say: "Flagged with 89% confidence because the account pairing (Cash/Office Supplies) is rare for this user and occurred at 2:00 AM."
This transparency is mandatory for a tool to be considered a "competent" evidence source. You cannot simply say "the computer said so." You must provide the underlying logic that the machine used to reach that conclusion.
Architecture: The AI Audit Pipeline
Modern intelligence implementation follows a multi-stage pipeline designed to handle complex enterprise data structures.
No. Modern AI pipelines sit on top of existing SAP, Oracle, or NetSuite environments, pulling data via secure APIs without disrupting core operations.
The Six Stages of Intelligence
Implementing ai tools for audit requires a resilient data architecture. You cannot simply point an LLM at an ERP and expect a clean result. The process follows a specific pipeline:
[ERP DATA] → [ETL PIPELINE] → [UNIFIED SCHEMA]
                                      ↓
[VECTOR STORE] ← [NLP ENGINE] ← [ANOMALY MODELS]
       ↓
[RISK SCORING] → [AUDITOR VALIDATION] → [IMMUTABLE LOG]- Data Extraction (ETL): Securely pulling data from ERP systems (SAP, Oracle, NetSuite) via API or encrypted flat files.
- Normalization: Converting fragmented data into a unified schema (e.g., matching CRM "Customer ID" to ERP "Client Account").
- Vectorization: Converting text and numerical data into high-dimensional vectors for processing.
- AI Processing: Running the data through specialized anomaly detection and NLP models.
- Auditor Validation (HITL): A human auditor reviews flags, confirming or dismissing them to retrain the model.
- Immutable Logging: Recording every action in a tamper-proof log for regulatory review.
Case Study: AI Implementation at a Global Manufacturing Firm
Intelligence-led oversight delivers measurable ROI by identifying risks that manual sampling misses. To illustrate the ROI of ai and auditing, let's look at a hypothetical (but realistic) implementation for a company with $2B in annual revenue and 15 global entities.
The Challenge
The company was using a "Big 4" firm that sampled 500 transactions per entity, yet missed a $12M embezzlement scheme involving "phantom vendors" in Southeast Asia that lasted three years.
The Solution
Implemented a custom audit machine learning system that ingested 100% of JE data from SAP and integrated it with their procurement system.
The Result
Within 48 hours, the AI flagged 14 transactions sharing a common IP "Digital Signature," leading to the discovery of the scheme and recovery of $4.5M.
PCAOB AS 2310 and AI Confirmations
Modern intelligence systems simplify the verification of accounts receivable and cash balances through automated digital confirmations.
The PCAOB AS 2310 (The Auditor's Use of Confirmation) is a critical standard for verifying accounts receivable and cash balances. Traditionally, this was done via paper letters. AI is transforming this into a digital, secure process.
Modern tools can now automatically generate confirmation requests, track them via secure tokens, and use NLP to read the responses. If a respondent provides a partial confirmation or notes an "exception," the AI identifies the discrepancy and pulls the relevant supporting documents from the ERP automatically. This reduces the "confirmation cycle" from 30 days to under 48 hours.
Step-by-Step Guide: Implementing Automation
Transitioning to automated oversight is a multi-phase journey that requires process change rather than just a software purchase.
Phase 1: Data Strategy & Infrastructure
AI is a mirror. If your data is messy, your audit will be useless. This involves identifying data owners, building a secure Data Lake, and ensuring custom AI workflows have read-only API access.
Phase 2: Pilot Program (POC)
Pick a high-friction, low-complexity use case—like travel and expense (T&E) auditing. If the system can find a $50 dinner that was double-expensed, it can find a $50,000 fraudulent payment.
Phase 3: Regulatory Alignment & Governance
Audit methodology must be approved. Document the control environment, define model modification rights, and use AI consulting firms to bridge engineering and compliance gaps.
Phase 4: Full Deployment & Continuous Training
Scale to revenue and payroll. The key to long-term success is continuous training—the system must learn new "normals" as your business expands into new regions.
Checklist for Audit Committees
Governance boards must evaluate the efficacy and transparency of their automated compliance systems through rigorous questioning. If you are a board member or an executive, here are 5 questions you must ask your CAO and Internal Audit Director:
- What percentage of our transactions are currently analyzed by automated systems?Target should be 100%.
- How are we ensuring that our AI models are explainable to external regulators?Requires XAI (Explainable AI) documentation.
- What is our process for identifying and remediating algorithmic bias?Requires periodic bias audits with synthetic data.
- Do we have a 'Clean Room' environment for our financial data?To prevent leakage into public AI models.
- How has our risk profile changed since implementing continuous monitoring?Looking for reduction in time-to-detection.
Never use public AI models (like the free version of ChatGPT) for auditing. Your financial data is a trade secret. Always use enterprise-grade, "Sanitized" environments where your data is not used to train the public model.
The Future: AIOps and the "Self-Healing" Audit
By 2027, we expect to see "Self-Healing" audit systems that merge intelligence with operational automation to create businesses that are "Compliant by Design." These systems won't just flag an error; they will suggest the correction and, if authorized, automatically update the ERP and notify the relevant manager. This merges intelligence with operational automation, creating a business that is "Compliant by Design."
We are also seeing the emergence of "Cross-Company" AI auditing. If a vendor is flagged for fraud at Company A, the system can (anonymously) alert Company B that the same vendor is exhibiting suspicious patterns. This collaborative defense will make corporate fraud significantly harder to execute.
Key Takeaways
- AI auditing shifts the paradigm from sampling to 100% population testing.
- Real-time anomaly detection identifies risks months before a traditional audit would.
- Explainable AI (XAI) is mandatory for regulatory compliance and transparency.
- The future of auditing is 'Human-in-the-loop' (HITL) with autonomous agents.
Conclusion: The Future of Auditing and the AI Efficiency Shift
The integration of modern intelligence is the most significant change to the profession since the invention of double-entry bookkeeping. It moves the auditor from a "checker" to a "strategic advisor." By automating the mundane tasks of data matching and sampling, auditors can finally focus on the high-level risks that actually impact business value.
For organizations still relying on manual sampling, the risk of a material misstatement is growing every day. The volume of data is simply too large for humans to monitor alone. Embracing ai auditing tools is no longer a strategic advantage; it is a requirement for operational survival.
Shift your compliance from a once-a-year headache to a 24/7 competitive advantage. Start your AI transition with UseShift's compliance audit framework. Our team helps you build the bridge from manual overhead to autonomous efficiency through AI-powered content and operational bots.